MSC R&D specialist tax and technical team

Independent R&D
claim review.
Confidence through scrutiny.

An objective assessment of your current or previous R&D tax relief claim, drawing on specialist technical knowledge, chartered tax expertise and experience from former HMRC inspectors.

No charge for the review. No obligation to appoint MSC R&D.

Would your R&D claim stand up to scrutiny?

For established claimants, R&D tax relief can represent a significant financial benefit. Yet claims are often prepared year after year without an independent assessment of the approach taken.

A claim being processed and paid by HMRC does not necessarily mean that every element has undergone detailed scrutiny. HMRC can still enquire into the claim, and the strength of the company's position depends on the work carried out, how it has been explained and the evidence available to support it.

Our independent review gives businesses a clearer understanding of their current or previous claim, identifying areas that are well supported and aspects that may require further attention.

The specialists behind our approach.

The quality of an R&D claim depends on the experience of the people assessing it. At MSC R&D, former HMRC expertise is embedded in our quality assurance approach, supported by specialist tax and technical professionals.

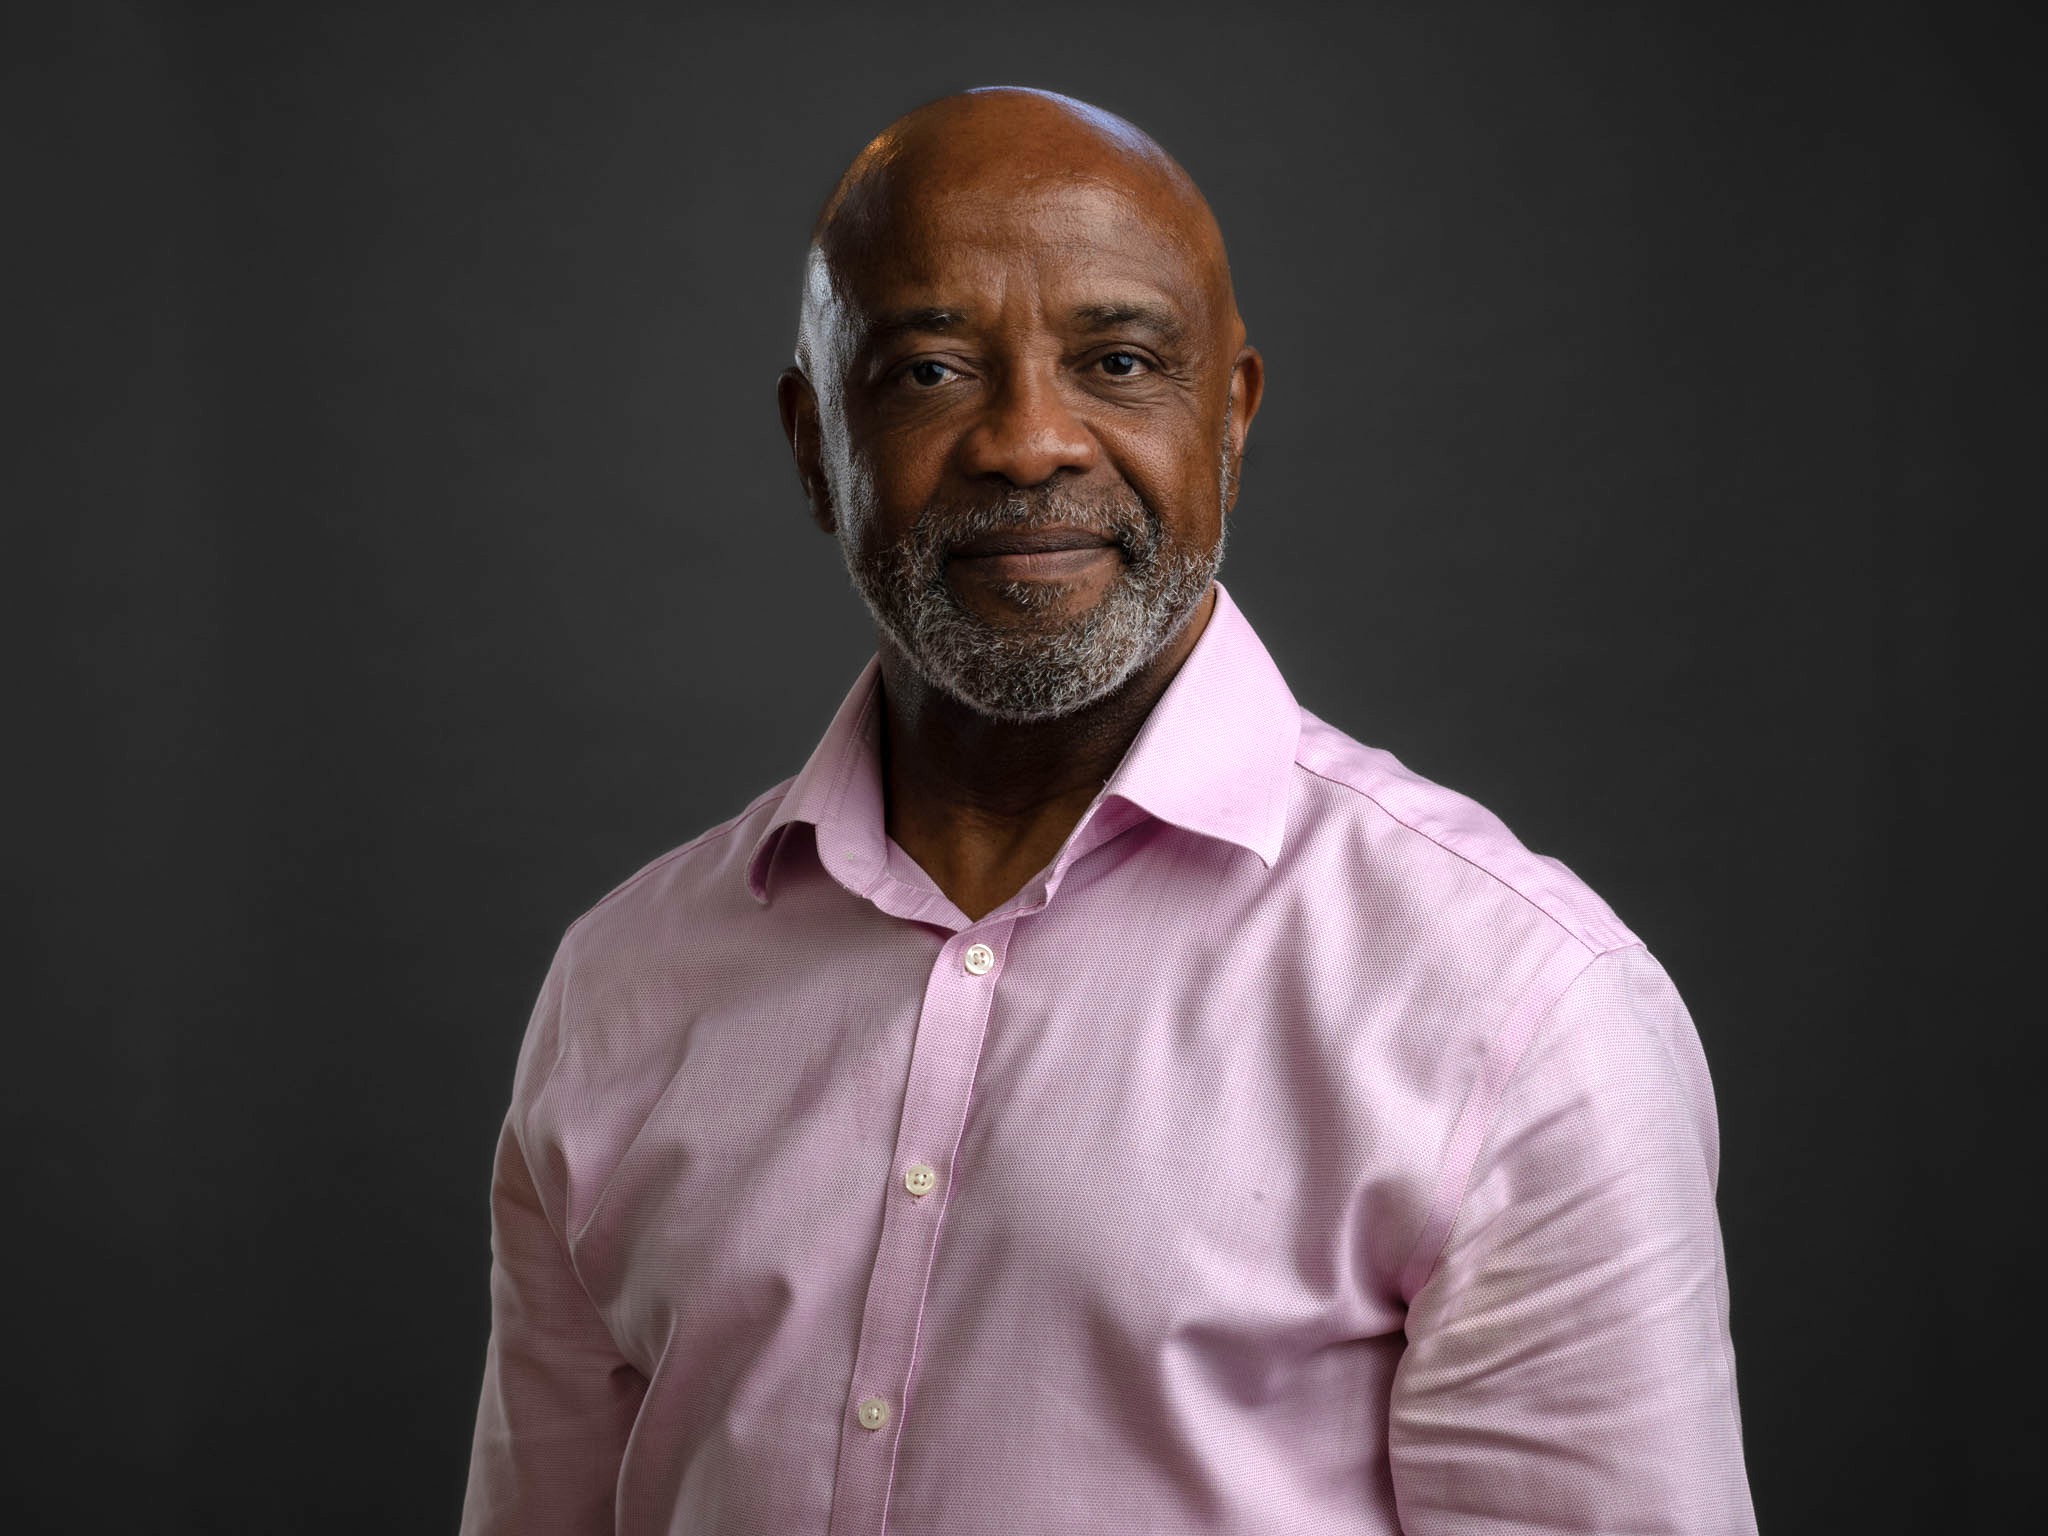
Peter Azu, Head of Quality Assurance at MSC R&D

Peter Azu

Head of Quality Assurance

Peter qualified as an HM Inspector of Taxes and worked in one of HMRC's specialist R&D units. He subsequently developed his R&D advisory experience in professional services, including roles at KPMG and AECOM.

At MSC R&D, Peter leads the quality assurance process, reviewing the technical and financial support behind claims. His work also includes HMRC enquiries, bringing practical insight into the evidence and explanations that may come under scrutiny.

Read Peter's full profile
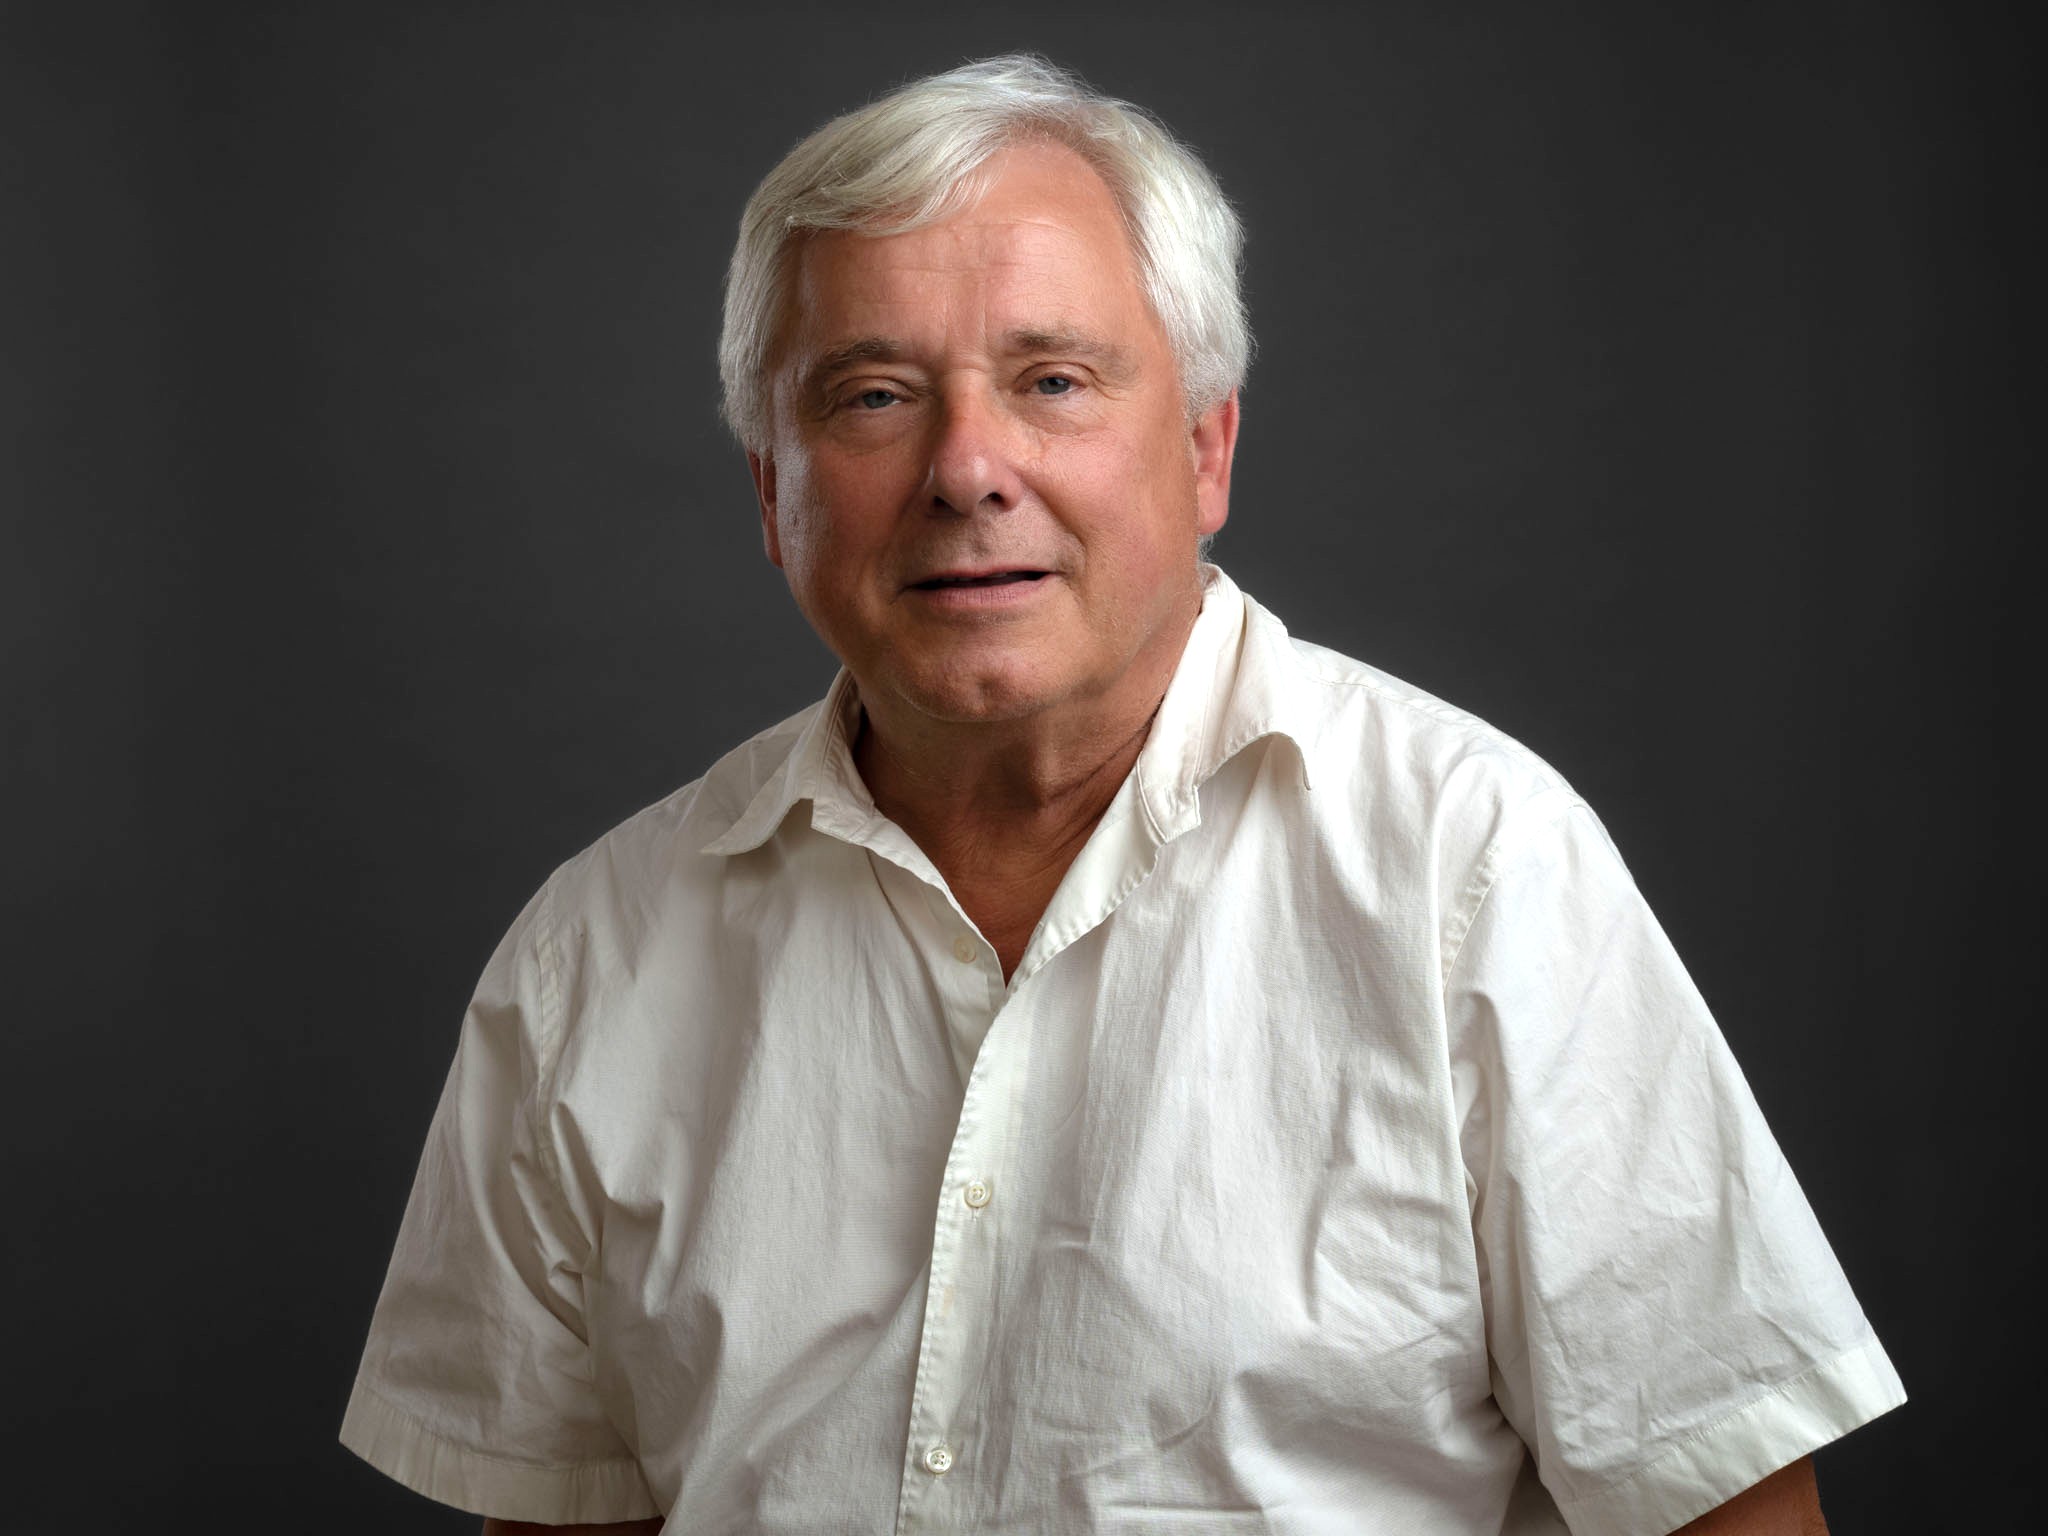
Gavin Bate, Expert Consultant to MSC R&D

Gavin Bate

Expert Consultant · Former HMRC R&D Technical Leader

Gavin has over 20 years' experience specialising in R&D tax relief. As HMRC's former technical leader for the regime, he co-authored the guidelines defining R&D for tax purposes and produced HMRC's CIRD instruction manual.

Gavin supports MSC R&D in a consulting capacity, providing specialist training and advice on complex matters of interpretation and HMRC enquiries. This gives our team access to detailed knowledge of the regime and its application.

Read Gavin's full profile

Peter and Gavin's expertise complements MSC R&D's wider team of experienced technical analysts and chartered tax advisers.

Meet our wider team

Why review a previous R&D claim?

Claims should accurately reflect the technological work undertaken, the uncertainties encountered and the qualifying expenditure incurred. An independent review examines how those elements have been presented and supported.

Technical accuracy

Does the narrative explain the technological advance sought, the baseline of existing knowledge and the uncertainties that could not readily be resolved?

Supporting evidence

Is there sufficient relevant documentation to substantiate the work undertaken and the information included in the claim?

Financial treatment

Have costs been identified and calculated in accordance with the relevant rules, with a clear connection to the qualifying activities?

Changes over time

Has the claim preparation process kept pace with developments in the business, its projects and the applicable guidance?

An assessment informed by genuine specialist experience.

Effective R&D claim analysis requires a detailed understanding of the science or technology, the tax treatment of qualifying expenditure and the information HMRC expects to see.

MSC R&D brings these disciplines together, with a compliance-first approach that places accuracy, consistency and supporting evidence at the centre of the review.

Technical understanding

Experienced technical professionals assess the advances and uncertainties described in the claim.

Specialist tax knowledge

Qualified tax advisers consider the relevant scheme rules and how expenditure has been treated.

Independent quality assurance

Experience from former HMRC inspectors contributes additional challenge and scrutiny to the assessment.

What do we look at?

Our review considers the technical and financial aspects of the claim, including whether the qualifying work has been appropriately defined, the expenditure calculated on a sound basis and the available evidence is consistent with the position presented.

Existing knowledge baseline

Whether the claim identifies the knowledge and capabilities already available in the relevant field.

Scientific or technological advance

How the advance sought has been defined, including the boundaries of the R&D activity.

Scientific or technological uncertainty

Whether the uncertainties are clearly explained, including how they developed and were addressed.

Technical narrative

The accuracy and consistency of the descriptions of the work carried out during the claim period.

Qualifying expenditure

The basis on which qualifying costs were identified, calculated and attributed to the R&D.

Supporting documentation

Whether project records, financial information and other relevant evidence support the claim.

When is a claim review particularly useful?

There are several points in a company's development when an independent perspective can be valuable.

Claims have increased in value or complexity

The scope of the company's technical work or the amounts claimed have grown over time.

Preparing for future submissions

The finance team wants greater confidence in the process before the next R&D claim is prepared.

Considering a change of adviser

The business wants an independent view of historic work before deciding on its future adviser arrangements.

Investment, due diligence or a sale

Historic R&D tax relief claims may receive closer attention as part of a wider transaction.

What you will receive from us

Following the review, you receive a written document outlining our findings, including any areas that may benefit from further explanation, supporting evidence or changes to the approach taken.

In some cases, our assessment provides reassurance that the existing claim is well supported. In others, we identify opportunities to improve the clarity, accuracy or compliance of the claim and future submissions.

There is no charge for the claim review and no obligation to appoint MSC R&D.

Initial discussion

We establish the scope of the claim and the documentation available for review.

Specialist assessment

The relevant technical, tax and evidential aspects are considered by our team.

Written findings

We provide a clear summary of the findings and discuss practical next steps.

Frequently asked questions

Does payment of an R&D claim mean HMRC has approved it?

No. A claim can be processed and paid without every element being examined in detail. HMRC may still open an enquiry within the applicable time limits and ask for evidence supporting the claim.

Can MSC review a claim prepared by another adviser?

Yes. Our independent review is suitable for businesses seeking a second opinion on a claim prepared by another provider, including businesses assessing their future adviser arrangements.

What information will you need?

This depends on the claim. We will discuss the relevant technical narratives, expenditure calculations and available supporting documentation during the initial conversation.

What will we receive after the review?

You receive a written summary of our findings. Where there is room for improvement, we explain the areas identified and provide recommendations for strengthening the claim.

Is there a charge or any obligation to change adviser?

No. The independent claim review is provided without charge, and there is no obligation to appoint MSC R&D for future work.

How confident are you in your R&D claim?

Speak with our specialist team about an independent assessment of your current or previous R&D tax relief claim.